Case File #001 · 2026-09-03
The Price Gap.
An appraisal says $2,450. A listing says $120,000. Neither number is lying — they are answering different questions. Case File #001 follows the gap: who produced each number, from what source, and what a buyer actually paid.
Same domain. Different price. Different story.
Fact footer: Illustrative figures. The real-world version of this gap is documented in source S1 below: five tools, one name, one day, a 51× spread.
Fact footer: An appraisal is one signal (S1, S3). A listing is another (S4). Neither tells the whole story alone.
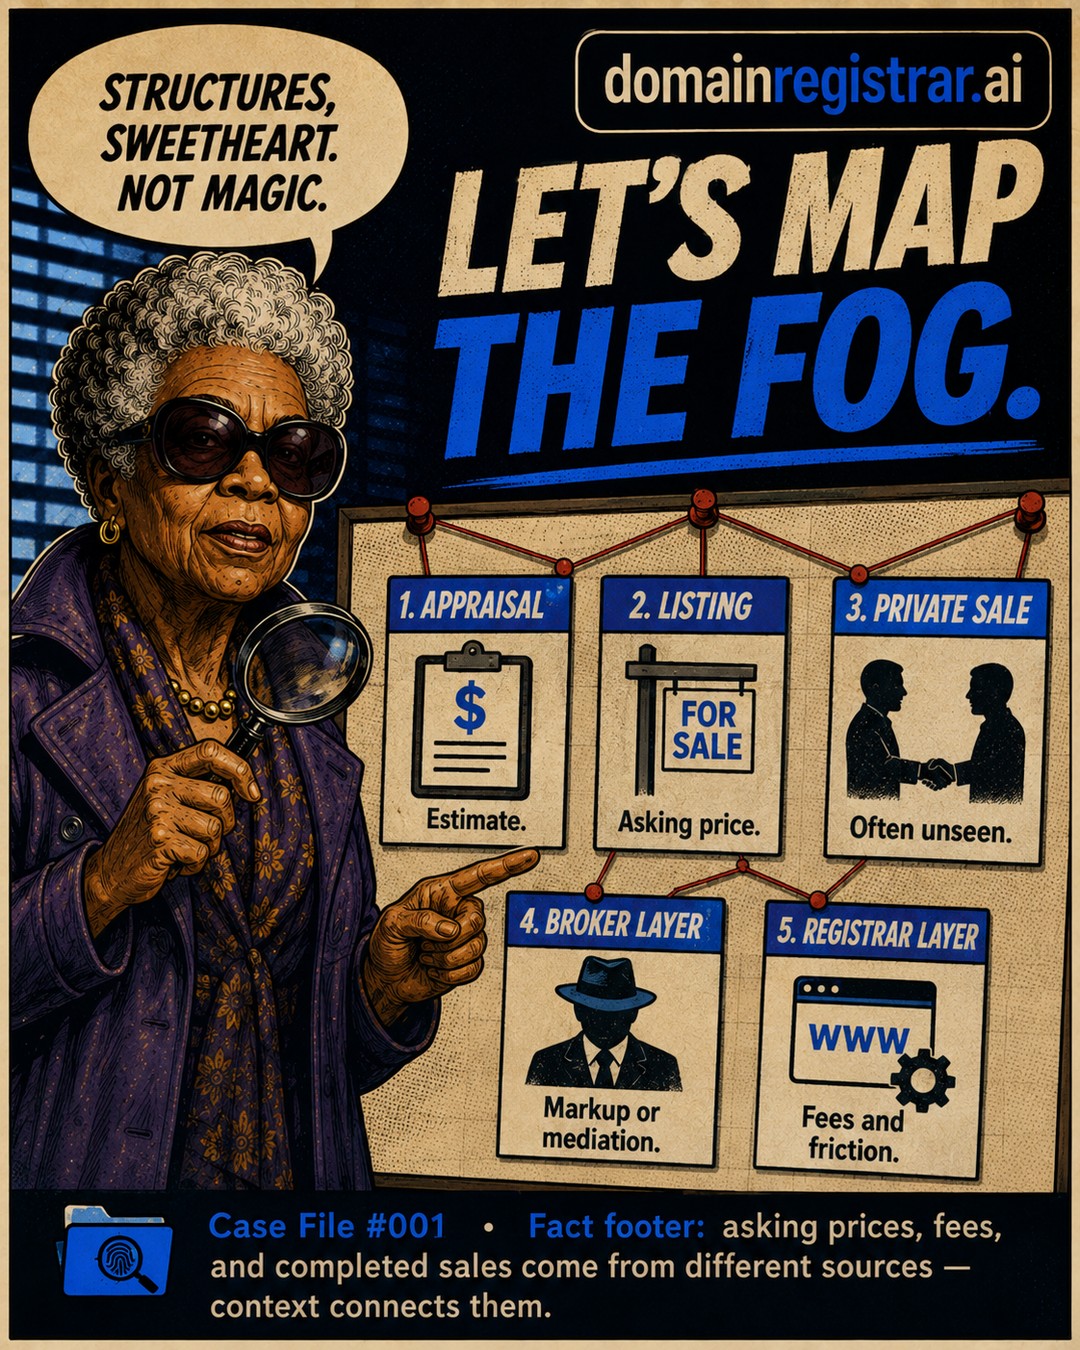
Fact footer: Asking prices, fees, and completed sales come from different sources — the venue split in S2 shows how differently they clear.
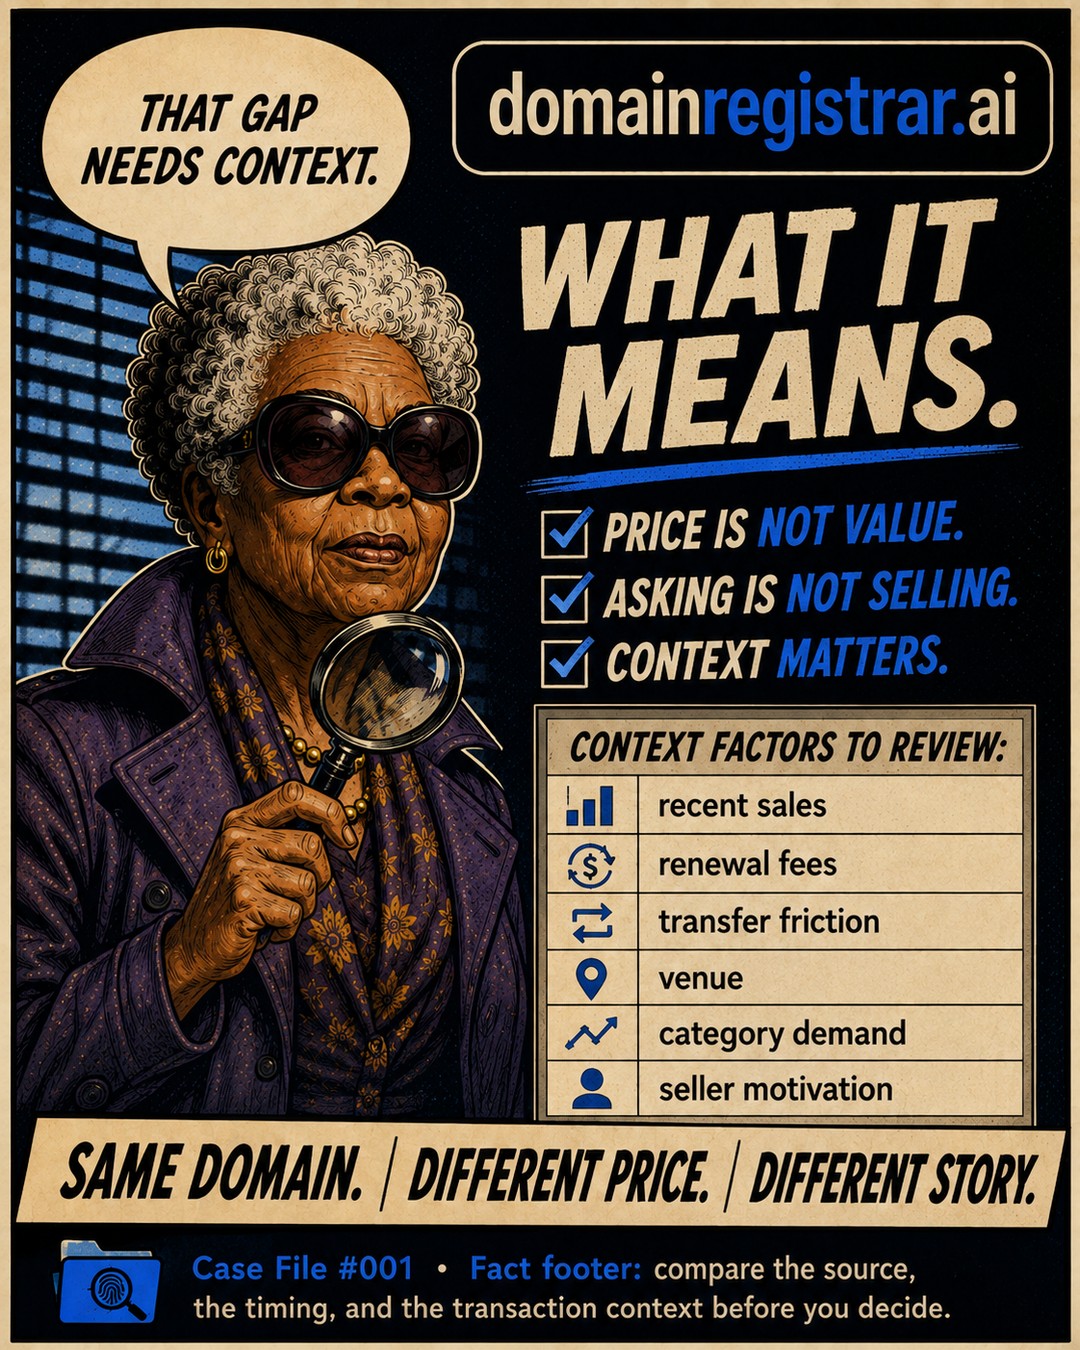
Fact footer: Compare the source, the timing, and the transaction context before you decide (S1–S4).
Fact footer: Source types the desk uses: public marketplace listings, reported sales data, registrar pricing pages, and public company filings (S2, S4, S5).
Fact footer: Source-backed context beats rumor every time. The grading vocabulary is in S6.
Fact footer: Fictional character · informational only · not legal, tax, or investment advice.
Receipts for this file.
- S1 — Five appraisals of one name (DomainPrice.ai), observed 2026-08-19: GoDaddy/GoValue $95 · HumbleWorth $890 · Dynadot $1,428 · EstiBot $3,700 · desk view $4,884PRICE_PROVENANCE_DOCTRINE, url.ventures, verified on book data 2026-08-19 · accessed 2026-09-03 · on this site →
- S2 — Desk corpus venue split — owner-listed vs registrar-auction/drop sales, raw and adjustedtools/adjusted_two_faces.py, run 2026-09-03 · accessed 2026-09-03 · on this site →
- S3 — "GoDaddy added a ton of new data to GoValue last month, which will have influenced valuations across the board" — James Iles (GoDaddy), May 4, 2023NamePros thread "Godaddy falling valuations" · accessed 2026-09-03 · source →
- S4 — NameBio reporting methodology — auctions captured automatically; Afternic/Dan sales only when a party reports; Sedo $2,000+NamePros discussions of NameBio data sources · accessed 2026-09-03 · source →
- S5 — Aftermarket revenue recognized on a gross basis; portfolio of more than 1.0 million domain namesGoDaddy Inc., Form 10-K FY2024, Items 1, 1A, 7, Note 2 (filed Feb 2025) · accessed 2026-09-03 · source →
- S6 — The desk's grading vocabulary — Primary-source confirmed · Multi-source reported · Party-reported · Marketplace observeddomainregistrar.ai disclosures · accessed 2026-09-03 · on this site →
Beyond the desk's corpus — what the record shows.
The largest registrar's annual report describes an aftermarket platform that "processes aftermarket, or secondary, domain name sales" while it "maintain[s] a portfolio of more than 1.0 million domain names," and provides "functionality for the entire registrar network to list expiring domains." Aftermarket revenue is recorded on a gross basis because the company "take[s] control of the domain" — it sells as principal, not only as agent — and it lists among its risks "increases in rates of failed sales… in which we act as the primary obligor, resulting in higher than expected domain portfolio assets."
GoDaddy Inc., Form 10-K FY2024 (filed Feb 2025), Items 1, 1A, 7 and Note 2 · accessed 2026-09-03Aftermarket revenue grew 5.0% in 2024 "due to increasing sales volume," then accelerated through 2025: $128M in Q1 (+5%, average transaction $321 vs $261 a year earlier), $119M in Q2, $136M in Q3 (+28%) as "large transactions returned."
GoDaddy 10-K FY2024 MD&A; Domain Name Wire, May 1 and Oct 30, 2025 · accessed 2026-09-03Effective February 1, 2023, the four marketplaces under one roof (Auctions, Afternic, Uniregistry, Dan) moved to 15% commission when the name points to the company's own nameservers and 25% when it does not.
GoDaddy blog, "Aftermarket alignment — update to commission model," Jan 4, 2023 · accessed 2026-09-03In early April 2023 the free appraisal tool was re-based: "GoDaddy added a ton of new data to GoValue last month, which will have influenced valuations across the board." Investors documented names that had shown above $1,000 printing under $100 afterward. In March 2024 the tool was capped at three free appraisals a day and stopped showing comparable sales.
James Iles (GoDaddy), NamePros, May 4, 2023; NamePros threads May 2023 and Mar 20, 2024 · accessed 2026-09-03The same company holds inventory at scale: the Uniregistry portfolio of ~350,000 names ($196.9M, 2020), ~200,000 names from Marchex ($281M), 70,000 from Most Wanted Domains ($30–35M, 2015) — and runs pricing experiments on "tens of thousands" of its own names against control groups, reporting a 22% revenue lift from charm pricing in the $2,500–$10,000 band.
GoDaddy press release Feb 11, 2020 (primary); Domain Name Wire; DomainInvesting.com; GoDaddy blog, Mar 29, 2023 (primary) · accessed 2026-09-03Public sales datasets lean toward the expiry stream by construction: auction results are captured automatically, while owner-listed sales on Afternic and Dan are reported only when a party volunteers them and Sedo reports only $2,000-plus. And on 118 real, publicly reported sales, two widely used third-party appraisers returned $0 on 70% of names that actually sold (EstiBot) and missed by a median of 100% and 94.5%; even the better of the two missed by 50% or more on 80% of names.
NameBio methodology notes; desk opacity study (composite_4way, Mar 2026) — attributed to the tools tested, not to any registrarThe desk states the structure and the record. It does not allege intent by any company and does not claim that any appraisal caused any lapse. Read it as arithmetic: a party that profits from expiry-and-resale, holds a seven-figure portfolio of its own, sells as principal, and also publishes the free number an owner sees at renewal has incentives that do not point the same way as the owner's. That is a market design problem — and the reason this desk exists.
Do something with it.
The DNS Detective is a fictional character. This case file is informational only and is not legal, tax, or investment advice. Nothing here promises value, appreciation, or a sale.